Consumer Trust, Data Security, and the Competition for Australian Super App Users
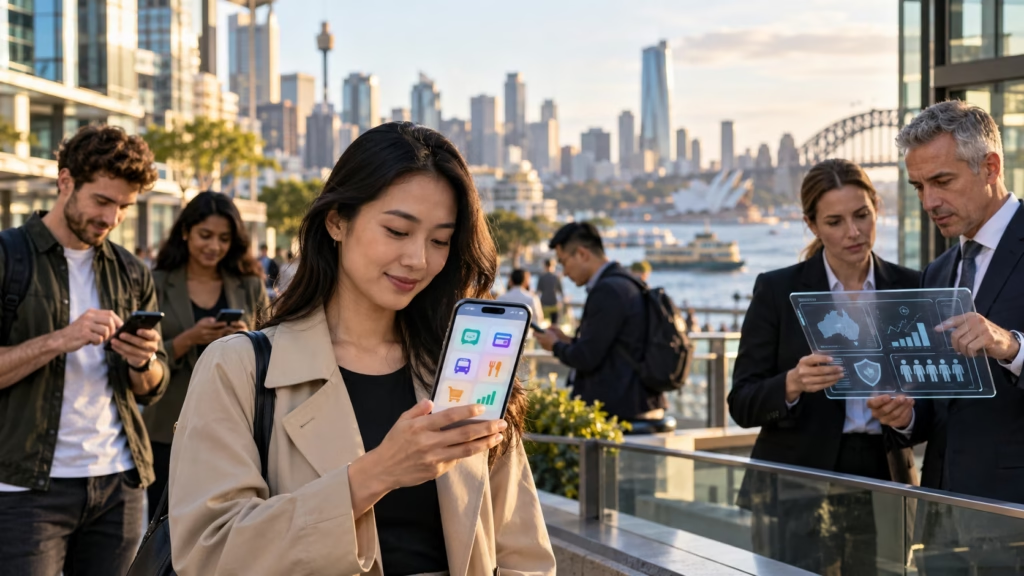
Australian consumers are simultaneously drawn to the convenience of integrated digital platforms and deeply concerned about the data security implications of concentrating their digital lives within a single application. This tension between convenience and caution defines the current super app landscape in Australia, creating both opportunities for platforms that can credibly address trust concerns and significant risks for those that fail to prioritise user protection. The eSafety Commissioner’s 2026 research on digital platform trust highlights that Australians are among the most privacy-conscious consumers in the developed world, a finding detailed at https://www.esafety.gov.au/.
Research published in January 2026 reveals that Australian shoppers weigh data security, trust, and digital experience heavily when choosing where to spend their money, particularly as retailers push more services through integrated digital channels. This finding has profound implications for super app operators: the feature-richness that makes integrated platforms appealing can simultaneously trigger privacy concerns that inhibit adoption. Success requires demonstrating that comprehensive service integration does not necessitate comprehensive data exploitation. Platforms that fail to thread this needle will find themselves stuck in a low-trust equilibrium where users limit engagement and resist deep integration.
Australian super app providers are responding to consumer sentiment by adopting stronger security measures and transparent privacy policies. Investments in encryption technology and adherence to national cybersecurity guidelines have become table stakes for platforms seeking to build and maintain user trust. Platforms that can articulate clear data governance frameworks, explaining exactly what data is collected, how it is used, and what safeguards prevent misuse, differentiate themselves in a market where generic privacy assurances are increasingly insufficient. The most sophisticated operators are now publishing regular transparency reports and submitting to independent audits.
A comprehensive multidisciplinary review published in 2026 synthesised findings from 177 publications to identify factors shaping super app user adoption and continued use. The research revealed that prevailing platform strategies, often built around closed ecosystems, raise significant questions about competition, data governance, and systemic resilience. For Australian operators, this suggests that the walled-garden model characteristic of Asian super apps may face greater resistance in a market with stronger privacy expectations and more competitive alternatives. Australian consumers want integration without lock-in, and they punish platforms that restrict their ability to move data or use competing services.
Beyond commercial platforms, Australian municipalities and government agencies are beginning to assemble local super apps that unify public service access. This parallel public sector trajectory offers citizens an alternative to private platforms for essential services, potentially reducing the pressure to adopt commercial super apps for tasks like transport, healthcare bookings, and government transactions. The emergence of public alternatives also provides a competitive check on private platform power, giving consumers meaningful choice about where to concentrate their digital activities. The Australian Digital ID system, for example, is being designed as a portable credential that works across multiple platforms rather than locking users into a single provider.
Super apps benefit from powerful network effects: more users attract more merchants, which attracts more users, creating a virtuous cycle that can rapidly entrench platform dominance. However, Australian consumer behaviour suggests that trust operates as a gating factor on these network effects. Until platforms clear a certain trust threshold, users resist the deep integration that makes super apps valuable. This creates a chicken-and-egg problem for new entrants and a vulnerability for incumbents that experience security incidents or privacy controversies. A single high-profile breach can undo years of trust-building and drive users back to specialised, lower-risk applications.
The platforms succeeding in the Australian market are those that give users meaningful control over their data and clear visibility into how their information is used. Granular privacy settings, transparent data practices, and robust security incident response protocols are becoming competitive necessities rather than regulatory afterthoughts. As super apps expand into increasingly sensitive service categories such as healthcare, financial planning, and identity verification, the trust bar will only rise higher. Platforms that treat privacy as a core design principle rather than a compliance checkbox will be best positioned to capture the Australian market.
Concentrating essential digital services within a small number of super apps creates systemic resilience concerns. If a dominant platform experiences an outage, security breach, or operational failure, the consequences ripple across multiple dimensions of users’ lives. Australian regulators and platform operators alike must address whether concentration of digital infrastructure enhances or undermines societal resilience. The answer will shape not only platform design but also the regulatory frameworks that govern them, with implications for competition, national security, and consumer welfare.